MISSION: HOMEOWNERSHIP
Impossible?
Not with B.O.M.B.
A clear, step-by-step guide to buying a home. Learn the process, build the right team, handle changes, and make informed choices.
EDUCATE. ADVOCATE. CELEBRATE.
We provide the tools. You make the move.

MISSION BRIEFING
Welcome to Mission: Homeownership
This is not a textbook. It is a simple guide you can use along the way.
Buying a home can feel hard when you face new words, different advice, changing rates, deadlines, inspections, underwriting requests, and many closing papers. The mission gets easier when you know your goal, understand the steps, build the right team, and know what to do when the plan changes.
MISSION PROGRESS
Homeownership is more than a house. It’s a stronger you, a stronger family, and a stronger community.
THE B.O.M.B. MESSAGE
B.O.M.B. exists to challenge negative ideas, build a culture of ownership, and celebrate brilliance. We educate people so they can understand the process, advocate so they can ask questions and stay involved, and celebrate the people who keep moving when the road gets hard.
The Three Pillars of Every Mission
EDUCATE
Knowledge changes the conversation. Learn the steps, the numbers, the papers, and the questions to ask.
ADVOCATE
When you understand more, you can use your voice. Know your options, speak up, and stay involved in your own transaction.
CELEBRATE
Owning a home is an accomplishment. Progress matters. Getting through hard moments matters. Getting the keys deserves to be celebrated.
YOUR ROLE: MISSION LEADER
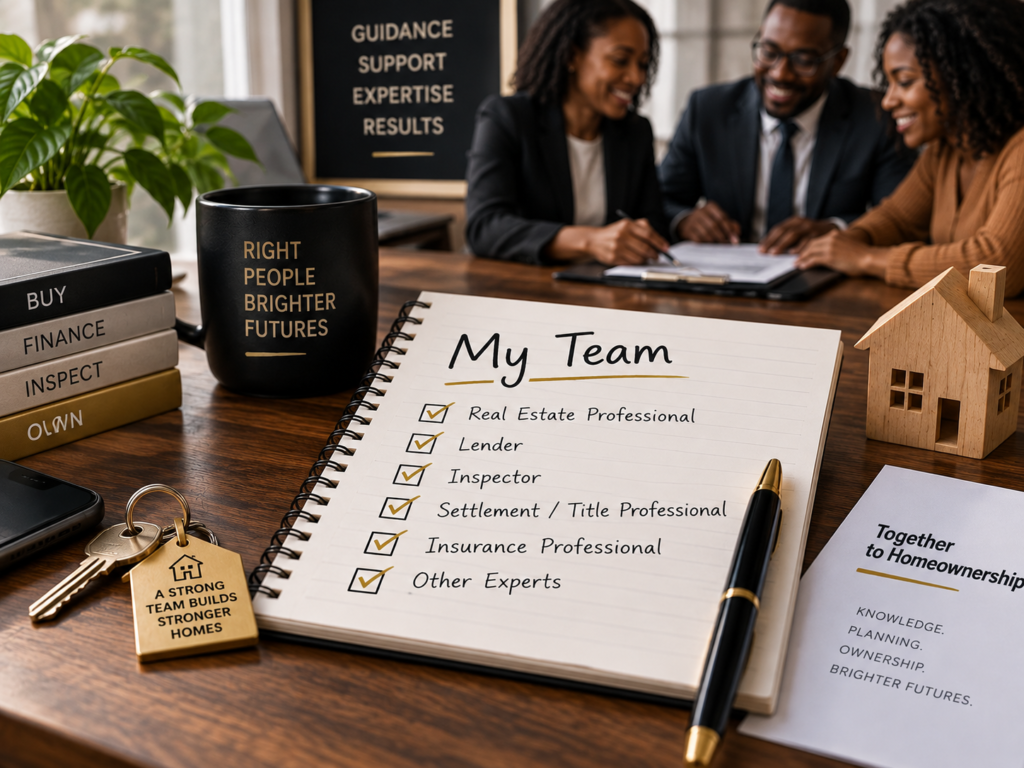
Your real estate professional, lender, inspector, settlement or title professional, insurance professional, and other experts may be on your team. But this is your home, your money, and your decision. You do not need to know everything. Stay informed, ask questions, understand the answers, and make choices you can live with.
THE B.O.M.B. CONTINGENCY PLAN
When something goes wrong: STOP. GET THE FACTS. KNOW YOUR OPTIONS. ASK THE QUESTION. MAKE YOUR MOVE.
IMPORTANT
B.O.M.B. is an education and consumer-advocacy platform. B.O.M.B. is not a mortgage lender. We do not guarantee a rate, loan approval, or outcome, and we do not make the final decision for you. Loan approval, pricing, underwriting, and property rules depend on your lender, loan program, financial profile, property, and market conditions.
MISSION MAP
Your Mission Roadmap
One goal. Many checkpoints. Keep moving.
MISSION 01
Know Your Objective
Educate
Every strong mission starts with a clear goal.
Start Mission
MISSION BRIEFING Before looking at homes, decide what homeownership needs to do for your life. Do not buy just because other people are buying. Know your why, your timing, your budget, and the responsibilities you are ready to take on. |
MISSION INTEL A lender may tell you how much you can qualify for. That is not the same as deciding what payment and home costs feel comfortable for you each month. |
What You Need to Know
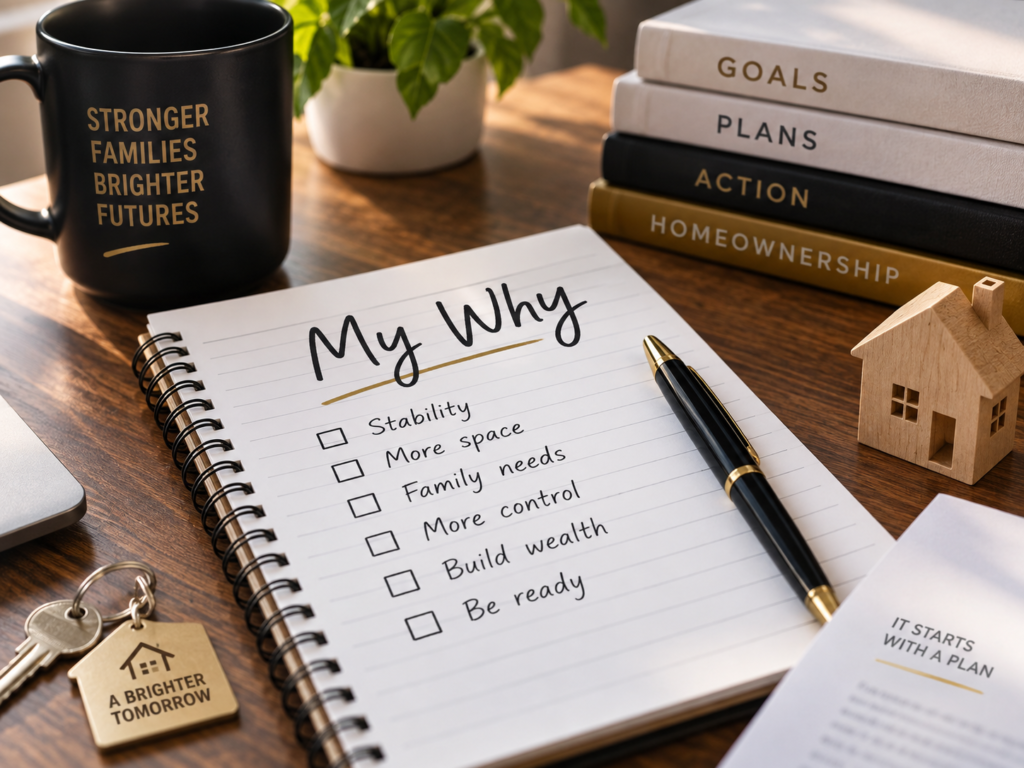
Start with your WHY — Know why you want a home. It may be stability, more space, family needs, more control, building wealth, or simply being ready. Write down what matters most.
Build a comfort payment — Plan for the full monthly cost, not just principal and interest. Include taxes, insurance, mortgage insurance if needed, HOA or condo dues, utilities, repairs, and commuting costs.
Protect your savings — Do not use every dollar to buy the home. Homes need repairs, and life brings surprises.
Set a realistic timeline — Your credit, savings, paperwork, lease, available homes, and the market can affect when you are ready.
MISSION ALERT Do not treat the largest amount you can qualify for as your personal spending goal. Qualification is a lender calculation. Comfort is your household decision. |
ASK THE QUESTION • What full monthly payment should I plan for, not just principal and interest? • What costs could change after closing? • How much money should I keep in savings after I buy? |
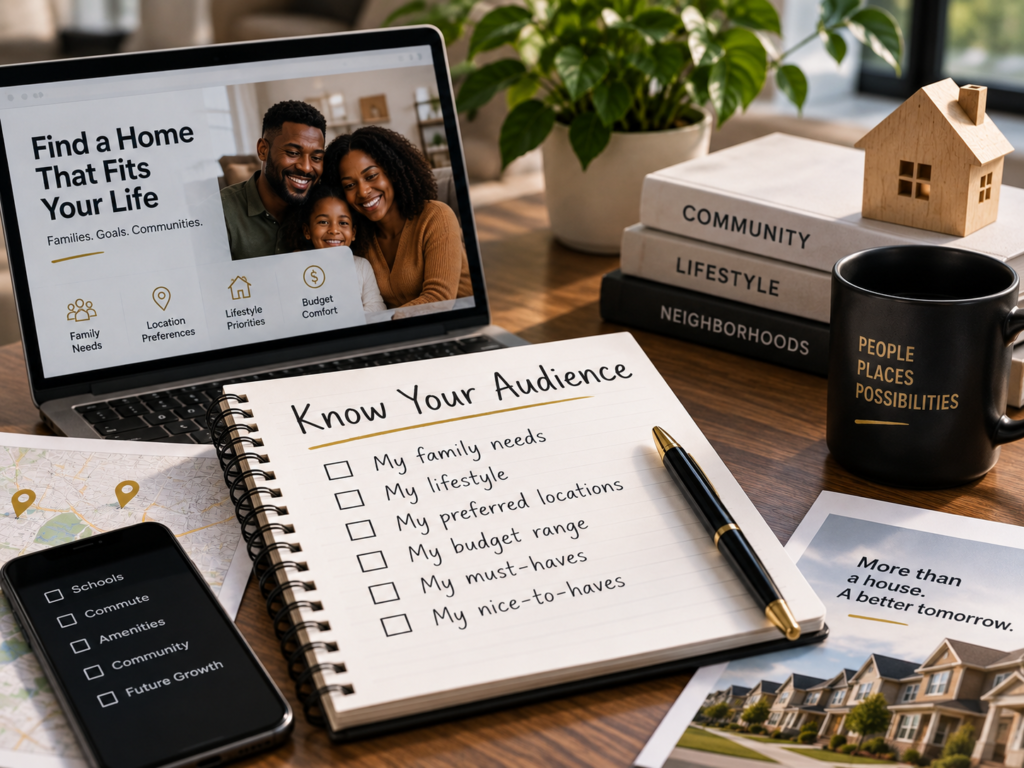
YOUR MOVE Write down three things your home must do for you, three things you would like, and the highest monthly housing cost you feel comfortable paying. |
MISSION CHECKPOINT I know why I want to buy, what I can comfortably afford, and what I will not give up just to become a homeowner. |
MISSION 02
Know Your Numbers
Educate
You cannot plan the mission until you know where you stand.
Start Mission
MISSION BRIEFING Mortgage underwriting has its own language: income, debt, assets, credit, and documents. Learn the basics before the conversation starts so surprises do not control the mission. |
MISSION INTEL Credit does not measure your value as a person. For a mortgage, it is one part of the lender’s risk review. Your goal is to understand what the lender sees and make sure the information is correct and can be explained. |
What You Need to Know
Income — Know how you are paid, how long you have earned that income, and what papers may be needed to prove it. Overtime, bonuses, commissions, self-employment, military pay, retirement income, and other income may be handled differently by each loan program.
Debt — Know the monthly debts on your credit report and any other regular payments that may count.
Assets — Know how much money you have for the down payment, closing costs, savings after closing, and emergencies. Be ready to show where the money came from.
Credit Love Language — Check your credit reports for mistakes. Understand your payment history and balances. Do not treat an online score as the only thing that matters.
Debt-to-income ratio — DTI compares certain monthly debts with the income a lender can use. It is helpful, but the limit can change by loan program, lender, and borrower.
MISSION ALERT Do not move large amounts of money, open new debt, or try to “fix” credit just because someone online told you to. A move that seems helpful can create paperwork problems or change the loan review. |
ASK THE QUESTION • Which income can be used to qualify? • Which debts are counted in my DTI? • Is there anything on my credit report I should explain or document before I apply? |
YOUR MOVE Make a one-page money snapshot: monthly income before taxes, monthly debt, cash available, emergency-savings goal, and any credit items you need to understand. |
MISSION CHECKPOINT I can explain my basic money picture before anyone else explains it to me. |
MISSION 03
Assemble Your Team
Advocate
A strong mission needs the right people, but you are still the mission leader.
Start Mission
MISSION BRIEFING Buying a home is a team effort. The goal is not to collect professionals. Know what each person does, who they represent, how they are paid, and whether they explain things in a way you can understand. |
MISSION INTEL A strong team should make hard information easier to understand. You should not feel like asking questions is a problem. |
Your Mission Team
TEAM MEMBER | MISSION ROLE |
YOU — Mission Leader | Stay informed, make decisions, protect your information, and speak up when something does not make sense. |
Real Estate Professional | Helps you search for homes, understand the market, plan offers, negotiate, track contract deadlines, and coordinate the transaction within their role. |
Loan Officer / Lender | Explains loan options, takes the application, gives required disclosures, works with processing and underwriting, and explains loan requirements. |
Home Inspector | Looks at visible parts of the home and points out concerns that may need more review. |
Appraiser | Gives an independent opinion of the home’s value for the lender. An appraisal is not a home inspection. |
Settlement / Title Professional | Handles title and settlement work, prepares or manages closing papers, and helps transfer ownership. |
Insurance Professional | Helps you get required insurance and understand the premium, deductible, and coverage. |
MISSION ALERT Do not assume everyone in the transaction has the same job, legal duty, or responsibility to you. Ask who each person represents and what they are responsible for. | |
ASK THE QUESTION • Who do you represent in this transaction? • How will you tell me when something changes? • What should I expect from you, and what do you expect from me? | |
YOUR MOVE Choose people who explain things clearly, communicate well, and respect your role in the transaction. Credentials matter. Communication matters too. | |
MISSION CHECKPOINT I know who is on my team, what each person does, and who to call when I have a question. |
MISSION 04
Get Cleared for the Mission
Educate
Understand the loan before you fall in love with a house.
Start Mission
MISSION BRIEFING Mortgage readiness is more than getting a letter. You should understand the financing well enough to know what you may be agreeing to before you make offers. |
MISSION INTEL A mortgage offer is more than the interest rate. Rate, APR, points, lender credits, loan term, mortgage insurance, closing costs, cash to close, and the lender’s timing can all matter. |
What You Need to Know
Prequalification vs. preapproval — These words can mean different things. Ask what the lender has actually reviewed and what the letter does, and does not, mean.
Loan options — Conventional, FHA, VA, USDA, Virginia Housing, and other programs have different rules, paperwork, property needs, insurance, and costs. The right program is the one that fits your situation.
Rate vs. APR — The interest rate helps set the interest you pay. APR is a wider measure that includes the rate and certain loan costs. APR can help you compare loans, but also look at the payment, points, cash to close, and loan features.
Points and lender credits — Points usually mean paying more at closing for a lower rate. Lender credits usually lower some upfront costs in exchange for a higher rate. Compare both choices based on how long you expect to keep the loan.
Loan Estimate — Use this form to review the loan you asked for and compare offers. If something looks different from what you discussed, ask why.
MISSION ALERT A low advertised rate can cost more if it requires points or fees you did not expect. Compare the whole offer, not just the headline rate. |
ASK THE QUESTION • Is my rate locked? If yes, until when? • What points, lender credits, and lender fees are included? • What is my estimated full monthly payment and cash to close? • What would change if I chose a different rate or cost option? |
YOUR MOVE Review your Loan Estimate line by line. Mark anything you cannot explain in your own words and ask about it. |
MISSION CHECKPOINT I understand the financing well enough to compare the whole offer, not just the rate. |
MISSION 05
Enter the Field
Educate
It’s about to be LIT — enjoy the search, but stay connected to the plan.
Start Mission
MISSION BRIEFING You have a goal, know your numbers, have a team, and understand the financing. Now the home search gets real. This is the fun part, and it is also where emotion can quickly outrun the plan. |
MISSION INTEL The right home is not only a home you love. It is also a property, location, payment, and responsibility you can live with after closing-day excitement fades. |
What You Need to Know
Needs vs. wants — Keep your goal in mind while you tour homes. A beautiful kitchen should not make you forget the commute, taxes, repairs, or payment.
Total cost of ownership — Ask about taxes, insurance, HOA or condo dues, utilities, maintenance, flood insurance if needed, and likely repairs.
Property condition — Look at the age and condition of major systems. A beautiful house can still need expensive repairs.
Location reality — Visit at different times if you can. Think about your commute, nearby services, the neighborhood, and how you really live.
MISSION ALERT Do not fall so deeply in love with a home that you stop looking at the numbers. |
ASK THE QUESTION • What regular costs come with this home besides the mortgage? • Are there HOA or condo rules or fees I should review? • What property problems should I look into before making an offer? |
YOUR MOVE For every serious home, do a quick B.O.M.B. check: PAYMENT — CONDITION — LOCATION — FUTURE COSTS — FIT WITH YOUR GOAL. |
MISSION CHECKPOINT I can be excited about a home and still review it like a mission leader. |
MISSION 06
Make Your Move
Advocate
You found a home. Now understand the contract before you sign.
Start Mission
MISSION BRIEFING An offer is more than a price. It includes money, deadlines, contingencies, responsibilities, and negotiation terms. The strongest move is not always the highest price. It is the move you understand and can support. |
MISSION INTEL Your first offer may not be your final offer. A seller can counter. Another buyer can win. You may decide the numbers no longer work. Losing one house is not the same as losing the mission. |
What You Need to Know
Purchase price — Know how the price affects your payment, cash needed, appraisal risk, and comfort level.
Earnest money — Know how much is required, where it is held, and when you could lose it under the contract.
Contingencies and deadlines — Inspection, financing, appraisal, HOA or condo review, sale-of-home, and other contract terms can create rights and deadlines. Ask your agent or attorney to explain the terms that apply to you.
Seller concessions — Seller credits may help pay allowed closing costs. The amount and use can depend on the contract and loan program.
Closing timing — Make sure the closing date works for the lender, seller, title or settlement team, and your moving plan.
MISSION ALERT Never sign because you feel rushed or embarrassed to ask what something means. A contract is not the place to pretend you understand. |
ASK THE QUESTION • What happens to my earnest money under the main contingencies? • What deadlines start when the contract is accepted? • What would make this offer too uncomfortable for my budget? |
YOUR MOVE Before you sign, be able to explain the price, earnest money, main contingencies, deadlines, seller credits, and expected closing date in plain language. |
MISSION CHECKPOINT I understand the offer I am making and what the main terms could mean for me. |
MISSION 07
When the Mission Goes Sideways
Advocate
Improvise. Adapt. Keep moving.
Start Mission
MISSION BRIEFING Almost no home purchase goes exactly as planned. Successful buyers are not people who never have problems. They slow down, get good information, understand their choices, and decide what makes sense next. |
MISSION INTEL The route can change without changing the goal. A different house, delayed closing, credit issue, or new financing plan may change the path without ending the goal of homeownership. |
When the Plan Changes
WHAT HAPPENED | B.O.M.B. RESPONSE |
Offer rejected | Regroup and review the plan. The goal has not changed. |
Inspection finds a major issue | Get the facts. Learn your contract rights and real choices. Decide based on cost, risk, and what you can handle. |
Appraisal comes in low | Ask about your contract and loan options. Depending on the situation, choices may include renegotiating, asking for a review, bringing more cash, or walking away. |
Underwriter asks for more documents | A condition is not automatically a denial. Ask exactly what is needed and send a complete response. |
Rate market moves | Get updated pricing. Compare the full offer and ask whether the lock decision should be reviewed. |
Your finances change | Tell the lender quickly. Hiding a change can create a bigger problem later. |
MISSION ALERT Panic can cause rushed choices. Silence leaves problems unanswered. When the mission changes, communicate. | |
ASK THE QUESTION • What exactly changed? • What choices do I really have? • What deadline applies? • What does each choice cost or risk? | |
YOUR MOVE Use the B.O.M.B. Contingency Plan every time: STOP. GET THE FACTS. KNOW YOUR OPTIONS. ASK THE QUESTION. MAKE YOUR MOVE. | |
MISSION CHECKPOINT I understand that a setback gives me information. It does not automatically end the mission. |
MISSION 08
Do Not Blow the Mission
Advocate
You have come too far to hurt your approval by mistake.
Start Mission
MISSION BRIEFING Once you are under contract, underwriting is checking the information in your application. Keep your money picture steady, answer requests, protect your information, and tell your lender before making changes that could affect the loan. |
MISSION INTEL Underwriting conditions are often requests to prove information, clear up differences, or complete the loan file. A condition is not automatically a denial. |
What You Need to Know
Keep credit stable — Do not open new debt or increase debt unless you first ask your lender how it could affect the loan.
Protect your job and income — A job or income change can affect your approval. Talk with your lender before making a change when possible.
Document money movement — Large or unusual deposits and transfers may need an explanation and proof.
Respond completely — Missing pages or partial documents can cause more requests. Follow secure upload instructions and keep copies.
Watch for fraud — Scammers often target buyers near closing. Verify suspicious requests and any changed wiring instructions using a phone number you already trust.
MISSION ALERT NO NEW CAR. NO NEW FURNITURE FINANCING. NO MYSTERY DEPOSITS. NO JOB SURPRISES. NO IGNORING THE LENDER. If you are not sure whether something matters, ask before you act. |
ASK THE QUESTION • Could this purchase or credit check affect my approval? • Do you need proof for this deposit or transfer? • Is anything still missing that could delay final approval? |
YOUR MOVE Before any major money change, call the lender and ask if it could affect approval, cash to close, or timing. |
MISSION CHECKPOINT I am protecting the financial picture that got me this far. |
MISSION 09
Know Before You Lock
Educate
Information gives you an advantage. The decision is still yours.
Start Mission
MISSION BRIEFING Mortgage markets move. B.O.M.B. rate information is designed to help you see what may be competitive so you can have a better conversation with your lender. |
MISSION INTEL B.O.M.B. is not the lender and does not guarantee a rate. Market information is not a promise that you will qualify for a certain rate or loan terms. |
What You Need to Know
Compare the same kind of loan — Loan type, term, occupancy, loan amount, credit, property type, points, lock period, and other details can change the price.
Use APR wisely — APR can help compare some loan costs, but it is not the only number that matters. Also review the rate, payment, points, fees, lender credits, cash to close, and how long you may keep the loan.
Understand the lock — Ask if your rate is locked, when the lock ends, and what happens if closing is delayed.
Use market information as a conversation tool — B.O.M.B. may show a Top 15 comparison based mainly on APR for an applicable scenario and share market updates. Use the information to ask better questions, not as a guarantee.
MISSION ALERT Do not chase a headline rate without knowing the cost. A lower rate may require more money upfront. A lender credit may lower upfront costs but raise the rate. |
ASK THE QUESTION • Is this rate locked? • What would this loan look like with fewer points or more lender credits? • How does this offer compare on APR, cash to close, and monthly payment? • If market pricing changes, what choices do I have before closing? |
YOUR MOVE Compare the full offer. Decide which mix of rate, cost, payment, timing, and service best fits your goal. |
MISSION CHECKPOINT I can use market information to ask better questions without treating it like a guaranteed offer. |
MISSION 10
Final Approach
Educate
You are close. Stay focused until the mission is complete.
Start Mission
MISSION BRIEFING Closing is not the time to stop paying attention. Final papers, final money, final home condition, and final fraud checks deserve the same focus that got you this far. |
MISSION INTEL For most covered mortgages, you must receive the Closing Disclosure at least three business days before closing. Use that time to compare the final terms and costs with what you expected and ask about important changes. |
What You Need to Know
Closing Disclosure — Review the loan amount, loan type, term, rate, payment, closing costs, lender charges, credits, deposits, and cash to close.
Final walkthrough — Make sure the home is in the expected condition and agreed repairs or items were handled as required.
Funds to close — Confirm the exact amount and approved way to send it. Verify wiring instructions through a trusted phone number.
Identification and documents — Know what to bring and keep copies of important closing papers.
MISSION ALERT A last-minute email that changes wiring instructions is a major fraud warning. Stop and verify the instructions using a phone number you already trust, not the number in the suspicious message. |
ASK THE QUESTION • Why did this cost change from my Loan Estimate? • Is my cash to close final, and how should I send it safely? • Is anything still missing that could stop or delay closing? |
YOUR MOVE Compare your final Closing Disclosure with your latest Loan Estimate. Write down every change you want explained before you sign. |
MISSION CHECKPOINT I know my final loan terms, the money I need for closing, and the last steps before I get the keys. |
FINAL MISSION
Mission Accomplished
Celebrate
Review. Ask. Understand. Sign. Get the keys.
Start Mission
MISSION BRIEFING You made it to the closing table. Do not rush just because people are waiting. Read what you sign, ask about anything you do not understand, and make sure the final deal matches what you agreed to. |
MISSION ACCOMPLISHED.
YOU MADE THE MOVE.
YOU’RE B.O.M.B.
CELEBRATE THE WIN Ownership is more than papers and keys. It can stand for preparation, sacrifice, strength, family goals, and the choice to keep moving when the process got hard. Take the picture. Play the anthem. Celebrate what you accomplished. |
THE B.O.M.B. MESSAGE B.O.M.B. exists to challenge negative ideas, build a culture of ownership, and celebrate brilliance. Education helped you understand. Advocacy helped you use your voice. Celebration honors what you accomplished. |
MISSION CHECKPOINT I finished the purchase knowing that what I learned is part of the accomplishment, and I can use that knowledge again. |
POST-MISSION 01
Protect What You Built
Celebrate
Closing ends the purchase. Ownership begins.
Start Mission
In the first months, the mission changes. Now you are protecting the home, protecting your money, and building stability.
First 90 Days: Homeowner Checklist
☐ Confirm how to make your mortgage payment and when it is due.
☐ Review your homeowners insurance, deductible, and contact information.
☐ Find the water, gas, electrical, and other important shutoffs or panels.
☐ Store closing, title, insurance, warranty, inspection, and major repair papers in a safe place.
☐ Build or keep an emergency repair fund.
☐ Make a simple home-care calendar for HVAC, filters, gutters, smoke and carbon-monoxide alarms, outside upkeep, and seasonal tasks.
☐ Watch for real tax, escrow, insurance, and mortgage-servicing notices. Verify suspicious messages before you act.
PASS THE INTEL FORWARD Tell future buyers what you wish someone had explained to you. Encourage them to compare the full mortgage offer, budget for the real cost of ownership, and ask questions when something is not clear. |
THE BIGGER B.O.M.B. MESSAGE Born from the Black experience. Built around ownership. Open to everyone who believes in what it represents. B.O.M.B. is for people who keep moving anyway. |
EDUCATE. ADVOCATE. CELEBRATE.
BE BOLD. BE BRILLIANT. BE B.O.M.B.
FIELD REFERENCE
B.O.M.B. Quick Glossary
Simple meanings for common words you may hear during the mission.
APR
A wider measure of loan cost that includes the interest rate and certain finance charges.
Appraisal
An independent opinion of the home’s value used by the lender. It is not a home inspection.
Cash to Close
The amount you bring to closing after deposits, credits, loan funds, and costs are counted.
Closing Disclosure
The final mortgage form showing key loan terms, payments, and closing costs.
Contingency
A contract condition that may give you rights or duties if a certain event happens.
Debt-to-Income Ratio
A comparison of certain monthly debts with the monthly income a lender can use.
Earnest Money
Money paid with or after the offer to show you are serious.
Escrow
Money held for a purpose — for taxes and insurance, or by a third party during the purchase.
Lender Credit
A credit that can lower some upfront costs, usually in exchange for a higher rate.
Loan Estimate
A standard form showing important terms and estimated costs for the mortgage you requested.
Points
Upfront charges based on a percentage of the loan amount, usually paid for a lower rate.
Rate Lock
An agreement to hold certain mortgage pricing for a set time, subject to the lock terms.
EDUCATE. ADVOCATE. CELEBRATE.
Your Move Starts Here
Knowledge today. Keys tomorrow.
Let’s make homeownership a reality.
About This Guide
This guide is original B.O.M.B. educational content. Its structure was informed by Virginia Housing homebuyer education, and mortgage disclosure topics were checked against Consumer Financial Protection Bureau consumer guidance. Loan limits, program rules and lender requirements can change — use official current sources for the latest details. MISSION: HOMEOWNERSHIP — Impossible? Not with B.O.M.B. is original B.O.M.B. branding and is not connected with any movie franchise.
EDUCATE. ADVOCATE. CELEBRATE.
BE BOLD. BE BRILLIANT. BE B.O.M.B.